

Europeans back slower bank checks to cut fraud risk
Fri, 2nd Oct 2026 (Today)
Most European consumers would accept slower bank verification checks in exchange for lower fraud risk, according to Fourthline, based on a survey of 6,000 adults across six markets.
It found that 78% of respondents would tolerate a slower, more thorough verification process if it reduced their exposure to fraud. Support was recorded across all markets surveyed, ranging from 72% in the UK to 80% in the Netherlands, and across all age groups, from 74% of those aged 18 to 24 to 79% of those aged over 55.
The figures point to a shift in consumer attitudes after years in which banks and fintech groups prioritised faster onboarding and less friction in account opening and identity checks. The research suggests many customers now place greater weight on security than speed when dealing with financial services.
Fourthline's study covered respondents in the UK, France, Germany, Spain, Italy and the Netherlands. Opinium conducted the fieldwork.
National differences
The results showed notable differences in how consumers balance trust, speed and security. UK respondents reported the highest trust in banks, with 83% saying they trust their bank to handle their money securely. Yet they were the least willing among the markets surveyed to accept slower checks, at 72%.
Only 53% of UK respondents said they wanted their bank to explain why extra security was needed. That suggests trust in financial institutions does not necessarily translate into patience with compliance procedures.
In the Netherlands, by contrast, respondents reported the lowest trust in banks, at 64%, but were the most willing to accept slower verification processes, at 80%.
In Germany, 78% said they would accept slower checks, while 71% said they would need to know why extra steps were necessary. German respondents were also the most likely to refuse a slower process altogether, at 15%.
The data indicates that consumers may be more accepting of additional checks when institutions explain their purpose clearly. Unexplained friction appears less acceptable than longer verification itself.
Generational split
The survey also found differences by age. Respondents aged 18 to 24 were the least willing to accept slower verification, with 74% in favour, despite being the group most exposed to fraud-related threats. More than one-fifth, or 22%, said they had been subject to financial fraud, while 30% said they had encountered AI-generated scams.
Older consumers showed the reverse pattern. Those aged over 55 faced the lowest reported risk of both financial fraud and AI-generated scams, at 13% and 8% respectively, yet were the most willing to accept a slower, more secure process, at 79%.
The contrast suggests that consumers with the highest exposure to newer forms of fraud are not necessarily the most prepared to tolerate added checks. That could present a challenge for banks seeking to tighten controls without losing younger customers during onboarding or account access.
Demand for explanation
The research also found a decline in support for security measures when framed in broad terms. The share of consumers willing to tolerate additional security protections fell to 42% from 55% in the earlier survey, according to Fourthline.
At the same time, willingness to accept a slower, more thorough verification process remained strong. That gap suggests consumers may be drawing a distinction between generic security measures and specific checks explained in the context of fraud prevention.
For banks and fintech groups, the findings may add to pressure to improve how they communicate identity and compliance checks to customers. Institutions have spent much of the past decade trying to reduce onboarding delays, but the survey indicates that some customers may be willing to trade speed for reassurance if they understand the reason for the delay.
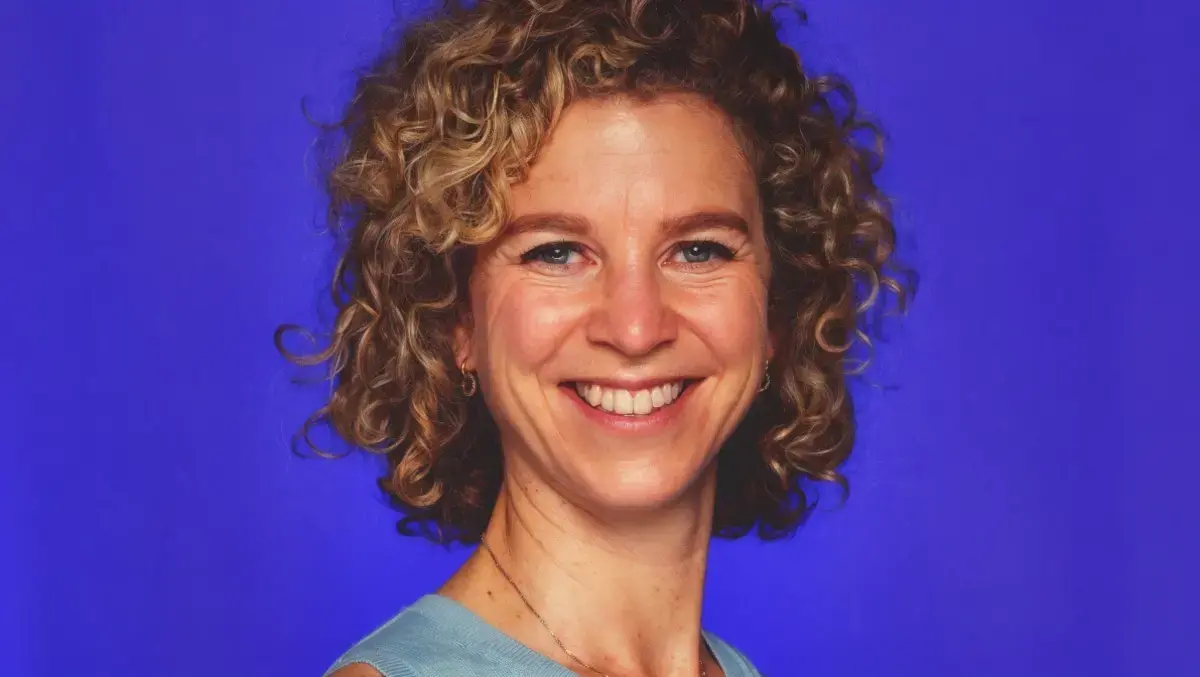
Fleur de Roos, Chief Operating Officer at Fourthline, said: “European customers say that, when it comes to security and identity verification, they want a meaningful process they understand. Speed is important, but it is not the top priority. Accessing money securely should not feel like an obstacle, but banks and financial institutions need to get these steps right to build trust and credibility with customers, tailored to different market and demographic needs. Fourthline is built on a mission to deliver safe, customer-centric identity verification, where seamlessness and security are compatible rather than competing. Our research shows that European consumers agree.”